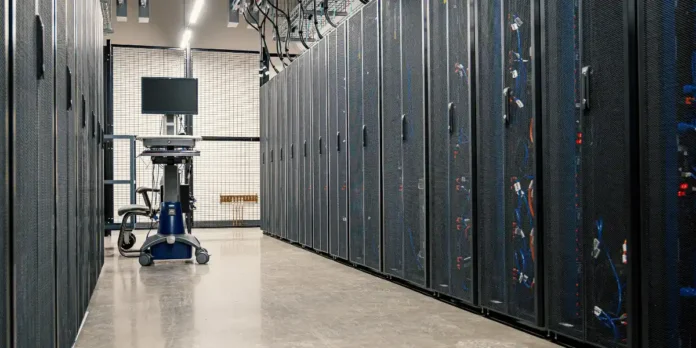
New Delhi, Oct. 6: India is likely to add more than 200 MW of data centre capacity in the second half of 2026, taking the country’s operational capacity towards 2 GW by the end of the year, according to a report by CBRE South Asia Pvt. Ltd.
The country added around 130 MW of new data centre capacity during the first half of 2026. More than 200 MW is expected to come online in the second half, putting India on track to reach approximately 2 GW of operational data centre capacity by year-end.
Mumbai accounted for 94 per cent of the new supply added during the first half of the year, reinforcing its position as India’s leading data centre hub, the report said.
The sector attracted nearly $38 billion in investment commitments during H1 2026, taking cumulative commitments since 2021 to approximately $173 billion. Hyperscale and colocation segments accounted for close to 62 per cent of the cumulative commitments, while more than 15 per cent were linked to demand from artificial intelligence.
“India’s data centre sector continues to scale at a pace few markets in the region can match,” said Anshuman Magazine, Chairman and CEO, India, South-East Asia, Middle East and Africa, CBRE.
Magazine said the country’s cumulative investment commitments of more than $170 billion, Mumbai’s continued leadership and increasing AI-linked investments indicated that the market was expanding while also becoming more mature.
The report noted that India has moved from being classified as a “High Growth Market” to the “Leading Data Centre Markets” category in Asia Pacific in 2026. India has joined Japan, Australia and Mainland China in the category.
Investor interest in data centres has also remained strong. The sector ranked as the fourth most preferred asset class in CBRE’s 2026 Asia Pacific Investor Intentions Survey.
The report pointed to increasing sophistication in India’s data centre infrastructure, with Tier IV facilities accounting for 43 per cent of overall supply in H1 2026, up from 21 per cent in 2024.
Multi-city portfolios accounted for more than 85 per cent of investment commitments during the first half of 2026, indicating growing interest in geographically diversified data centre assets.
Domestic investors continued to account for the largest share of cumulative capital deployed in the sector since 2021, at 38 per cent, followed by investors from the United States at 27 per cent.
Domestic developers also supplied 48 per cent of the new data centre capacity added in H1 2026, ahead of American and European developers.
The growth in capacity and investment is being supported by rising demand for cloud services, digital infrastructure and artificial intelligence applications, with the report indicating that AI-related requirements are becoming an increasingly important component of the sector’s investment pipeline.